Get Email Updates
Get an email the instant your dream home hits the market with your MyLogin account
Updated October 16, 2026 11:14AM EST



16 OCT
All Residential Properties
St. Lucie County’s residential real estate market moved at a more measured pace in September 2026, with fewer completed sales, longer selling times and a slight decline in the median sale price.
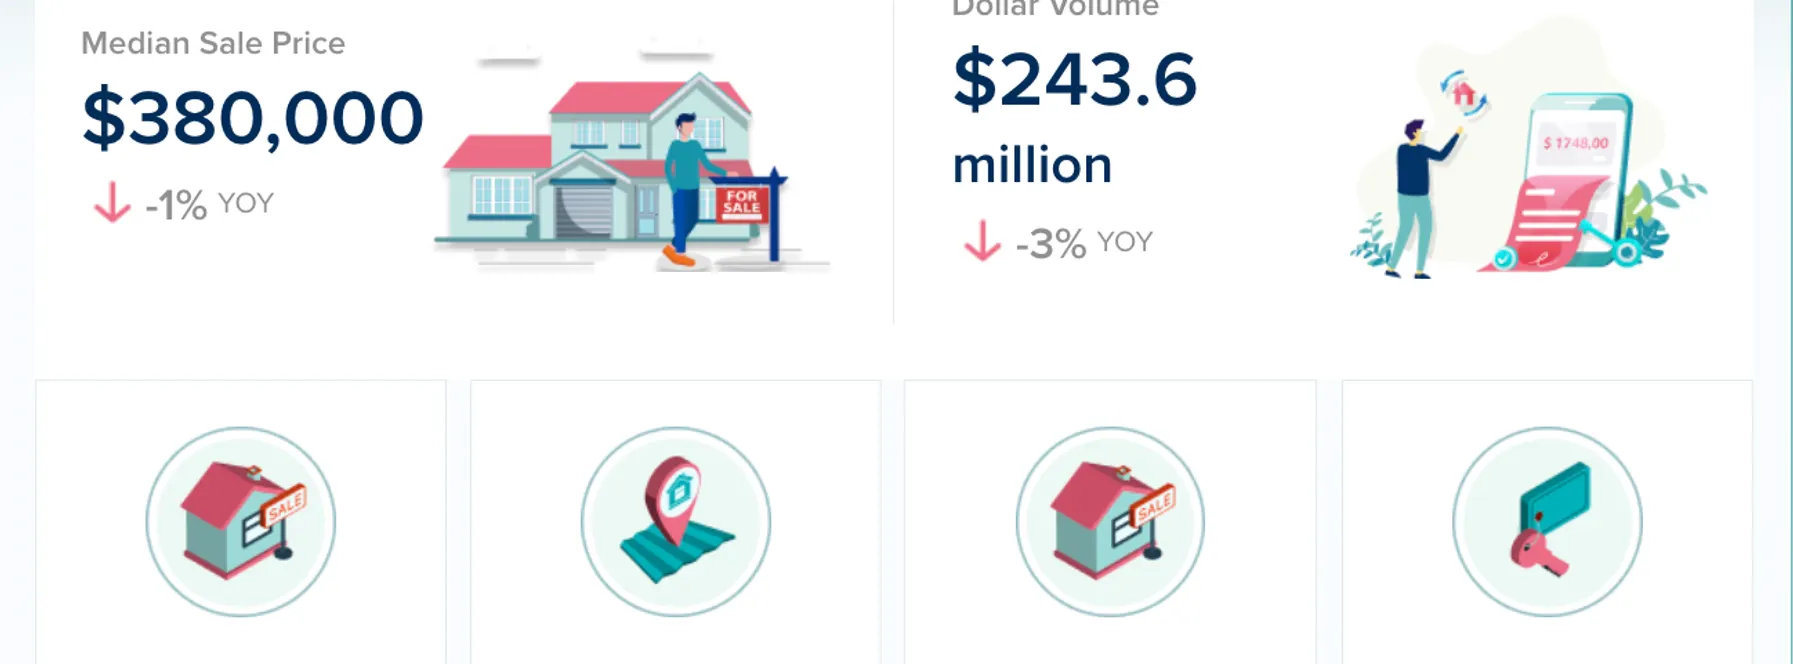
Across all residential property types, the median sale price reached $380,000, down 1% year-over-year. Closed sales declined 8%, while days on market increased 16%, suggesting properties that successfully sold took longer to find buyers than they did last September.
However, the market also showed signs of stability. Pending sales remained unchanged from a year ago, as did the number of new listings. Active inventory declined 5%, and months of supply fell 10%.
The defining feature of September’s market is that homes are taking longer to sell, even though available inventory has declined and buyers are entering into contracts at roughly the same pace as last year.
There are also some striking differences between the single-family and condo/townhome sectors, particularly when it comes to median prices and selling times.
Here’s a closer look at what September’s numbers mean for St. Lucie County buyers, sellers and investors.
🔻 Down 1% year-over-year
The median sale price across St. Lucie County’s residential market reached $380,000 in September, a modest 1% decline compared with September 2025.
The overall change is relatively small, suggesting the countywide median has remained fairly stable despite slower sales activity.
However, the two major property sectors recorded very different results.
Single-family homes reached a median of $395,000, down 1%, while condos and townhomes recorded a median of $337,500, up an impressive 24%.
The sharp increase in the condo and townhome median is particularly interesting, but it should be interpreted carefully.
With just 91 attached-home closings during September, changes in the types and price ranges of properties sold can have a substantial impact on the median.
The countywide median is also influenced by the mix of single-family homes, condos, townhomes and other residential properties sold during the month.
For buyers and sellers, recent comparable sales within a specific neighborhood or community remain a more useful guide to individual property values than the countywide median alone.
🔻 Down 8% year-over-year
St. Lucie County recorded 586 residential closed sales in September, an 8% decline compared with last year.
This indicates that fewer residential transactions were completed than in September 2025.
Both major property sectors contributed to the reduction, although the single-family market experienced the larger decline.
Single-family closed sales fell 9% to 464 homes, while condo and townhome closings declined 3% to 91 properties.
The reduction in completed transactions is worth monitoring, particularly because pending sales have remained stable.
Closed sales reflect transactions that were negotiated and progressed through the closing process, while pending sales provide a more current indication of properties under contract.
The difference between these two measures suggests that current buyer activity may be holding up better than the completed-sales figures alone indicate.
🔻 Down 5% year-over-year
Active residential inventory declined 5%, leaving St. Lucie County buyers with fewer available properties than they had a year ago.
However, this is a relatively modest reduction compared with the much sharper inventory declines recorded in Palm Beach and Martin counties during September.
The two major property sectors also experienced different changes.
Single-family inventory declined just 1% to 2,384 homes, while condo and townhome inventory fell 11% to 635 properties.
This suggests that the overall reduction in supply has been more pronounced in the attached-home sector.
For buyers, the available selection remains relatively close to last year’s level in the single-family market, while condo and townhome options have narrowed more noticeably.
For sellers, competition varies significantly depending on property type, location and price range.
Importantly, lower inventory has not translated into faster selling times across the county.
⏸️ Unchanged year-over-year
Pending residential sales totaled 562 in September, unchanged compared with September 2025.
This is one of the more encouraging statistics in the report.
Although completed sales declined 8%, the number of properties under contract has remained steady.
That suggests current contract activity has held up better than the closed-sales figure might imply.
There are also differences between the two major property sectors.
Single-family pending sales declined 2% to 446 contracts, while condo and townhome pending sales increased 6% to 85.
The increase in attached-home contracts provides an encouraging contrast with the slight reduction in single-family activity.
However, not every pending contract ultimately closes, and the timing of completed transactions can vary.
As St. Lucie County moves into the final quarter of 2026, it will be worth watching whether stable pending activity translates into stronger closing numbers.
🔻 Down 10% year-over-year
Months of supply declined 10% compared with September 2025.
This statistic measures how long the current inventory would take to sell at the prevailing pace of sales.
A reduction generally indicates less supply relative to market activity.
However, the decline was not uniform across property types.
Single-family months of inventory fell 5%, while condo and townhome supply declined 18%.
That reinforces the picture of a market where attached-home inventory has tightened more noticeably than single-family supply.
Yet September’s longer selling times demonstrate that reduced months of inventory does not necessarily mean every property will sell quickly.
Buyers can have fewer overall choices while still taking more time to evaluate individual listings.
📈 Up 16% year-over-year
Days on market increased 16%, making it one of September’s most important statistics.
Residential properties that successfully sold spent longer on the market than they did in September 2025.
However, the difference between property types is particularly striking.
Single-family days on market increased 18%, while condo and townhome selling times rose an extraordinary 70%.
The attached-home increase deserves attention, especially because condo and townhome inventory declined 11% and pending sales increased 6%.
The county is not necessarily lacking buyers, but properties that successfully sell are taking longer to complete the journey from listing to contract.
For sellers, longer marketing periods reinforce the importance of realistic pricing, property condition and strong presentation.
For buyers, the slower pace may provide opportunities to compare listings, conduct thorough inspections and negotiate thoughtfully.
However, days on market measures properties that successfully sold and does not guarantee that every active listing will follow the same pattern.
⏸️ Unchanged year-over-year
St. Lucie County recorded 820 new residential listings in September, unchanged from September 2025.
This suggests that the overall flow of new properties entering the market has remained relatively steady.
Within the two major sectors, single-family new listings increased 2% to 655 homes, while condo and townhome new listings rose 4% to 128 properties.
Despite those increases, the broader All Residential total was unchanged, reflecting differences across the property categories included in the countywide figures.
For buyers, a steady flow of new listings means fresh opportunities continue to become available.
For sellers, it means competition from newly listed properties remains an important consideration.
If longer selling times persist, even a stable level of new listings could influence how much inventory remains available in the months ahead.
St. Lucie County buyers may find a more measured market than those shopping in some neighboring South Florida counties.
Days on market have increased 16%, while the median sale price has declined slightly and pending sales remain unchanged.
That combination suggests buyers may have opportunities to compare properties and negotiate without feeling pressured to make immediate decisions.
However, the experience varies by property type.
Single-family inventory is almost unchanged from last year, while condo and townhome inventory has declined more substantially.
Buyers considering condos or townhomes should also investigate HOA fees, reserve funding, insurance, special assessments, maintenance obligations and rental restrictions.
A property that appears attractively priced may have ownership costs that significantly affect affordability.
The best approach is to be prepared financially while evaluating each opportunity carefully.
St. Lucie County sellers should pay particular attention to September’s increase in selling times.
Closed sales are down 8%, and days on market have risen 16%, even though active inventory has declined.
This suggests buyers are taking more time to make decisions.
For sellers, realistic pricing and strong presentation are particularly important.
Properties that are priced above current market expectations may struggle to attract interest, especially when buyers can compare alternatives.
The differences between property types also matter.
Single-family homes are taking longer to sell, while condo and townhome selling times have increased even more dramatically.
For attached properties, clear information about association fees, insurance, reserves and community finances can help buyers evaluate the overall cost of ownership.
For investors, St. Lucie County’s slower residential market may create opportunities to evaluate potential purchases more carefully.
Longer selling times can sometimes provide additional negotiating flexibility, particularly when a property has been listed for an extended period.
However, the relatively stable countywide median and differing trends between property types reinforce the importance of property-specific analysis.
Investors should evaluate acquisition price, financing, insurance, property taxes, maintenance, potential repairs and realistic rental income.
For condos and townhomes, HOA fees, special assessments, reserves and rental restrictions can have a particularly significant effect on returns.
Rather than relying solely on countywide percentage changes, investors should focus on the financial fundamentals of each property and its surrounding neighborhood.
St. Lucie County’s September 2026 residential market is moving more slowly, but several important indicators remain relatively stable.
The median sale price declined 1% to $380,000, while closed sales fell 8% and days on market increased 16%.
Active inventory declined 5%, and months of supply fell 10%.
Meanwhile, pending sales and new listings were both unchanged compared with September 2025.
The contrast between longer selling times and stable pending activity is particularly interesting.
Homes are taking longer to sell, but buyers are still entering into contracts at approximately the same pace as last year.
The differences between property types are also important.
Single-family homes recorded modest price movement and relatively stable inventory, while condos and townhomes experienced a substantial increase in their median sale price alongside dramatically longer selling times.
For sellers, realistic pricing and effective marketing remain essential in a market where buyers appear willing to take more time.
For buyers, longer selling times may provide opportunities to evaluate properties carefully and negotiate, although desirable, appropriately priced homes can still attract attention.
As St. Lucie County moves into the final quarter of 2026, the key trends to watch will be whether stable pending sales translate into stronger completed transactions and whether longer selling times begin to influence inventory and pricing.
For now, St. Lucie County’s residential market is characterized by measured buyer activity, longer selling times and meaningful differences between its single-family and attached-home sectors.
3 Beds | 2 Baths
Contact Andrew at ..
Offered at $1,350,000
More Info
5 Beds | 3 Baths
Contact Iryna at ..
Offered at $1,275,000
More Info
4 Beds | 2 Baths
Contact Allison at ..
Offered at $640,000
More Info

or Create your MyHomes account today?
In only 30 seconds you will have full access to property, community info and SOLD data you can't get anywhere else.