Get Email Updates
Get an email the instant your dream home hits the market with your MyLogin account
Updated October 16, 2026 11:14AM EST


10/08/2026
Jeff Lichtenstein
Oct 08, 2026
The Shilin Night Market in Taipei has all sorts of foodie forbidden pleasures. The clam’s slimier cousin, the oyster, starred in its own omelet. Oodles of noodles, Dim sum delights with soup packed into the wonton. Stinky Tofu if you want to get rid of your partner (it smells awful). Squid on a stick. Bubble Tea (the best one we had had the bubbles made from brown sugar). Mango shaved ice was amazing. Green onion and egg scallion pancake crepes. The list goes on and on.
Taiwan has recently been in the news. But it hasn’t been for its food scene. With the USA in the war with Iran and talk about Greenland, Canada, and Cuba – where does that leave itty bitty Taiwan? Does China take over?
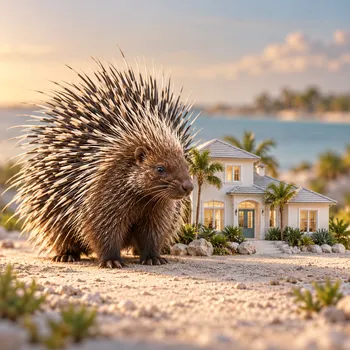
A few weeks ago, we visited Taipei. I asked our tour guide and driver about the situation. The tour guide said at one point during the Cold War maybe it was about democracy. Today we realize America is like “boyfriend”. Boyfriend gets some fun with our semiconductors but eventually boyfriend leaves. China is probably the long-term marriage partner. But that doesn’t mean Taiwan is without options. They have lots of military weapons and can inflict much short-term damage with its porcupine strategy. All males over 16 years of age are enlisted in the military. The culture is wildly democratic. I visited Hong Kong in 1994 and Taiwan I think will be a harder transition. It’s just not as orderly of a society as Hong Kong was as I remember it. Plus, the exact date of the Hong Kong transition was set. Taiwan isn’t a set takeover. Eventually a politician or two or three gets paid off. The timing is right and then you have a new boyfriend.
In distressed and challenging personal situations, housing markets go through similar stress fields. Every year or two I get asked about short sells and foreclosures. Buyers think it’s a way to make a fast buck but like the porcupine strategy, there are other strategies to keep the house or get out. And you must be aware of the consequences when going in for the kill if you want to buy one of these. Usually, it’s not the bargain one thinks it is. Here are 7 Porcupine strategies to be aware of in more unconventional situations.
1. Foreclosures
People will call and say, I want to buy a foreclosure. I say why? Foreclosures are usually sub properties that are dated, with lesser views, and not in the most desirable locations. They have frequently sat vacant for months or years. In Florida’s climate, that can mean mold, pest infestations, deferred maintenance, missing appliances, damaged plumbing (often from copper pipe theft), and a landscape in disarray. Bank-owned (REO) properties are often priced to sell, which is part of their appeal. But what banks price away in purchase price, buyers sometimes pay back in remediation costs. And the bank typically sells as-is with minimal disclosure obligations. The math has to work. A 10% discount on the purchase price that comes with $30,000 in remediation costs isn’t a deal; it’s a trap. A thorough inspection and honest cost estimation before any offer is non-negotiable.
2. Short Sales
This is an explanation I go through and have to take a deep breath. A short sale occurs when a seller owes more on their mortgage than the home is worth, and their lender agrees to accept less than the full payoff. From a buyer’s perspective, the appeal is a potentially discounted price. The challenge is the timeline.
Short sales require lender approval, sometimes multiple lender approvals if there are second mortgages or other liens. The process is document-heavy, communication-intensive, and can take months from accepted offer to closing. During that time, the seller’s lender controls the pace, and that pace is often slow.
Can you continue shopping while a short sale is under contract? In most cases, yes, the seller will often accept other offers as backup. And once approval comes through, do you have the right to cancel? Generally, yes, within specified windows, but understanding exactly what your contract says is critical.
3. Reverse Mortgage
You know you’re getting older when you can start to relate to the actor who is pitching reverse mortgages. Now it’s Henry Winkler (The Fonz). Yikes. You can have a house full of equity and a checking account running on fumes. For some older homeowners, a reverse mortgage can help close that gap. The most common type, a Home Equity Conversion Mortgage, is available to qualifying homeowners age 62 and older. It lets you borrow against your equity without making monthly principal and interest payments. If the proceeds are sufficient, they can pay off the existing mortgage and remove that monthly payment.
But the house doesn’t suddenly become free. You still have taxes, insurance, maintenance, and any association fees. Interest and fees get added to the loan balance, so the debt grows. The loan generally comes due when the home is sold or the last borrower dies or moves out, subject to protections for eligible spouses. Fail to meet the ongoing requirements and foreclosure is still possible. Have a HUD-approved reverse mortgage counselor walk through the numbers. It can be a useful tool, but you need to understand what you and your family are signing up for.
4. Family Member
Sometimes the help is sitting across the Thanksgiving table. A family member may be able to lend money to catch up on payments, help with expenses, or purchase the home so you can remain there under an agreed arrangement. If the problem is temporary, that breathing room might keep a difficult few months from becoming a forced sale.
But ‘we’ll work it out’ is not much of a financial plan. Is the money a gift or a loan? When does it get repaid? If a family member buys the house, who pays the taxes, insurance, repairs, and rent? Put the terms in writing with an attorney and have an accountant review the tax implications, including any interest requirements on a family loan. Check the mortgage terms before changing ownership. Family help can save a house. A vague agreement can make the next Thanksgiving very uncomfortable. But if you can’t stand Uncle Edmond, it can also be a way of going to the next Thanksgiving meal by asking for moola.
5. Refinance
A refinance replaces your current mortgage with a new one. A lower interest rate or a longer repayment term may bring the monthly payment down to something manageable. If you have enough equity and qualify, a cash-out refinance may also provide money to address other bills. But you are borrowing that money, not finding it under the couch.
The math has to work here, too. Compare the payment savings with closing costs, the new loan balance, and the total interest over the life of the loan. Stretching payments over more years can cost more overall, even when the monthly bill looks better. And replacing a low-rate mortgage with a higher-rate one just to get cash deserves a very hard look.
Timing matters. Missed payments, reduced income, or damaged credit can make approval harder. Talk to a lender before you are deep in the hole. If refinancing isn’t available, ask your existing mortgage servicer about a loan modification or other hardship options. One concern about this is prices haven’t gone up in housing as much as inflation recently. Also, there is a trend with lower money down over the years. With AI replacing some secure jobs, this gives homeowners less of a safety net here.
6. LLC
People hear ‘LLC’ and think they have found a force field. A limited liability company can be useful for holding investment property or bringing investors together. For example, investors might purchase a distressed property through an LLC, with the sale proceeds used to pay off the seller’s mortgage. That is a sale with a different ownership structure. It isn’t a disappearing act for the debt.
Putting your own house into an LLC does not erase the mortgage, release your personal loan obligations, or stop a lender from foreclosing. A transfer can also trigger a mortgage’s due-on-sale clause, depending on the loan terms and applicable rules. In Florida, it can affect homestead tax benefits and protections. Before moving a deed around, have a Florida real estate attorney review the mortgage, ownership, and tax consequences. An LLC may belong in an investment plan. By itself, it is not a rescue plan for a homeowner behind on payments.
7. Bridge Loans
Sometimes the problem is timing. You have equity in the house you are selling, but you need money before that sale closes. A bridge loan is short-term financing that can help span that gap, commonly allowing you to buy the next home before selling the current one. Some lenders also offer short-term loans against equity while a sale is pending. Qualification and terms vary.
The bridge has a toll. These loans generally carry higher interest rates and fees than a conventional mortgage, and the balance may be due in one large payment at the end. If the house takes longer to sell or brings less than expected, your exit plan can get expensive quickly. You may also be carrying costs on two homes.
Know how the loan gets repaid before taking it out. Use a realistic sale price, allow for delays, and understand what happens at maturity. A bridge can solve a timing problem. It won’t fix a house that is overpriced or a budget that no longer works.
All of these strategies are nuanced. Just give us a call if you need to use a porcupine strategy as we don’t want you to make a mistake and get into a prickly situation!


Jeff Lichtenstein, originally from Chicago, got his start in the home furnishings textile business where he traveled over 35 weeks a year selling fabrics. After the family business was sold, Jeff moved to Florida and became a real estate agent. Today he is the owner and broker of Echo Fine Properties, a luxury residential brokerage voted best brokerage of the year. Jeff manages a non-traditional model of real estate that mimics a traditional business model. Echo has 100 agents, an average of one million dollars per transaction and over 500 million in annual sales. Between traveling for work and annual family trips to national parks with his wife and 2 now adult children, Jeff has visited 49 states. He is also one of the few Chicago White Sox fans you’ll ever meet. Some publications he has been quoted in.
Author of business & leadership book How Making a Sandwich Can Change Your World – The Amazing Success of the PB&J Strategy – Available to Buy Now!
Feel free to ask him a question directly at [email protected] including a complementary valuation of your home.

or Create your MyHomes account today?
In only 30 seconds you will have full access to property, community info and SOLD data you can't get anywhere else.