Get Email Updates
Get an email the instant your dream home hits the market with your MyLogin account
Updated November 16, 2026 10:40AM EST



16 NOV
Miami-Dade County’s overall housing market experienced stable median prices, declining inventory and faster selling times in October 2026, despite a slowdown in completed transactions and pending contracts.
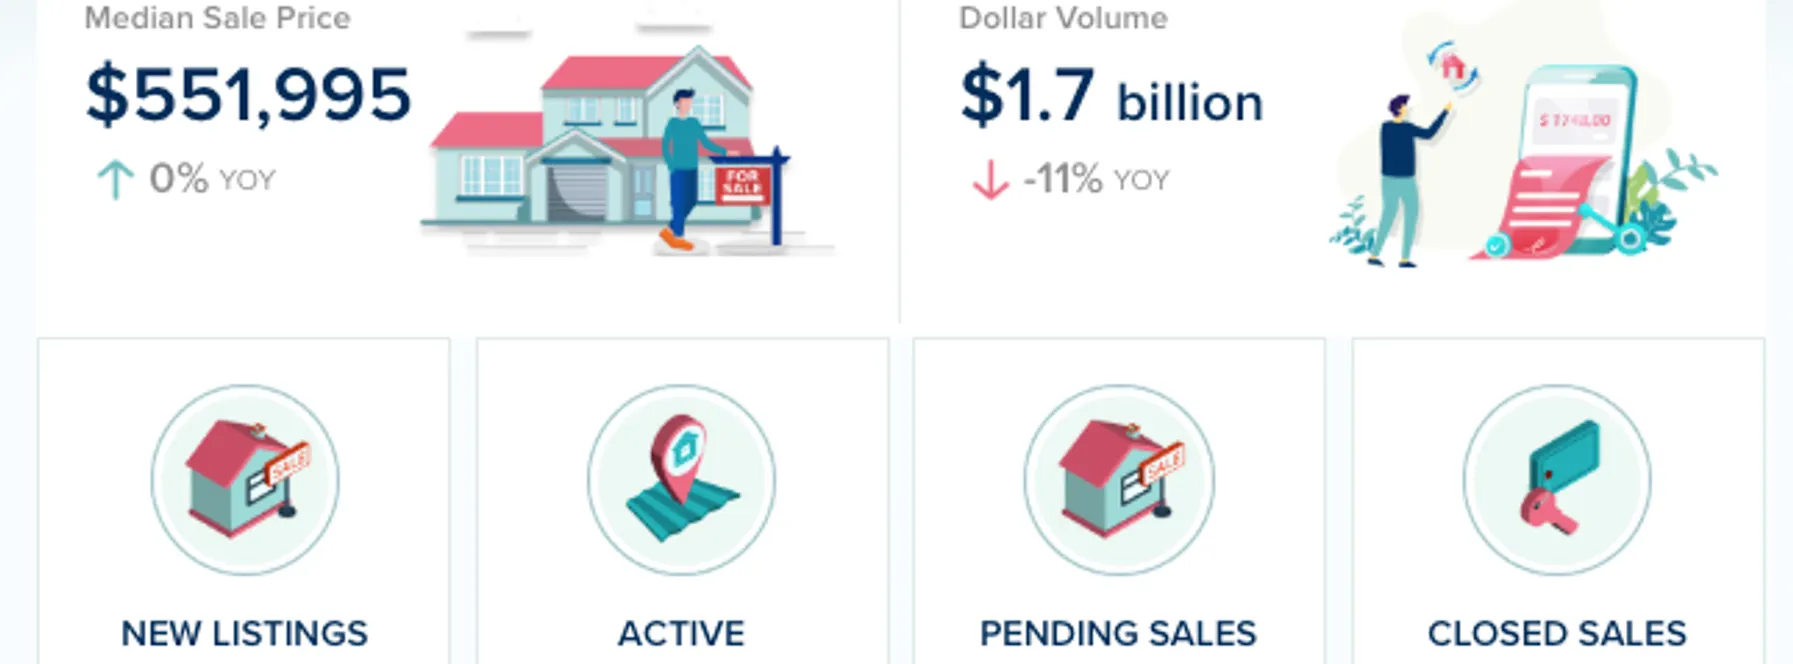
The median sale price across all residential property types reached $551,995, unchanged compared with October 2025. However, closed sales declined 11% to 1,691 properties, indicating that fewer transactions were completed even as the overall median price held steady.
Active inventory fell 8% to 16,779 properties, while pending sales declined 18% to 1,643 contracts. New listings also decreased 7%, indicating that fewer properties entered the market compared with the same period last year.
Meanwhile, days on market declined 12%, and months of inventory fell 12%, suggesting that available supply has tightened and properties completing sales are moving faster.
The biggest story this October is that Miami-Dade County’s overall median sale price has remained unchanged despite a meaningful slowdown in completed transactions and pending contracts.
There are also important differences between property types. Single-family median prices increased 4%, while condo and townhome median prices declined 1%.
Total residential sales dollar volume reached approximately $1.7 billion, an 11% decline year-over-year.
Let’s take a closer look at what these figures mean for Miami-Dade County buyers, sellers and investors.
➡️ Unchanged year-over-year
The median sale price across all Miami-Dade County residential property types reached $551,995 in October, unchanged compared with October 2025.
This indicates that the overall median price of properties sold remained stable despite softer transaction activity.
However, the countywide figure masks important differences between property types.
Single-family homes recorded a median sale price of $706,000, up 4% year-over-year.
Meanwhile, condos and townhomes reached $397,500, a 1% decline.
These figures demonstrate that the single-family sector experienced stronger median price growth than the attached-home sector.
The unchanged overall median may also reflect changes in the mix of properties sold across different categories and price ranges.
For buyers, stable countywide median pricing may provide some reassurance compared with markets experiencing substantial price increases.
For sellers, the figures reinforce the importance of evaluating recent comparable sales within their specific neighborhood or community.
However, the median sale price reflects the middle price of properties sold during the month.
An unchanged median does not mean every individual property has maintained exactly the same value.
Individual homes, buildings and communities may have experienced very different pricing trends.
🔻 Down 11% year-over-year
Miami-Dade County recorded 1,691 closed residential sales in October, representing an 11% decline compared with October 2025.
This indicates that overall completed transaction activity has softened.
The reduction was evident across both major property sectors.
Single-family closed sales declined 12% to 782 homes, while condo and townhome sales fell 10% to 907 properties.
These figures suggest that fewer transactions were completed across the broader market.
Total residential sales dollar volume reached approximately $1.7 billion, an 11% decline year-over-year.
The reduction in dollar volume matched the percentage decline in completed sales.
This indicates that the total value of completed transactions decreased at approximately the same rate as transaction counts.
However, the relationship was different within individual property sectors.
Single-family dollar volume declined 18%, while condo and townhome dollar volume fell just 2%.
This contrast highlights the importance of examining property categories separately.
For buyers and sellers, the figures demonstrate that countywide averages can conceal important differences in market activity.
🔻 Down 8% year-over-year
Active residential inventory stood at 16,779 properties in October, an 8% decline compared with October 2025.
This represents a reduction in the number of available properties.
With fewer homes on the market, buyers have less choice than they did a year ago.
However, the reduction was not evenly distributed between property types.
Single-family inventory declined 14% to 4,739 homes, while condo and townhome inventory fell 5% to 11,989 properties.
These figures indicate that available supply has tightened more substantially in the single-family sector.
For sellers, fewer competing listings may create a more favorable environment, particularly when properties are priced accurately.
For buyers, reduced inventory may require greater preparation and flexibility.
However, the unchanged overall median sale price demonstrates that reduced supply does not necessarily translate into higher prices across every property category.
Individual neighborhoods, buildings and price ranges can experience very different market conditions.
Understanding local inventory remains essential when evaluating buying or selling opportunities.
🔻 Down 18% year-over-year
Pending residential sales totaled 1,643 in October, an 18% decline compared with October 2025.
This is one of the most important indicators in Miami-Dade County’s overall housing report.
Pending sales represent properties that have gone under contract but have not yet completed the closing process.
Because of this, they can provide an indication of potential future transaction activity.
The decline suggests that fewer buyers entered into contracts compared with the same period last year.
The reduction was evident across both major property sectors.
Single-family pending sales fell 22%, while condo and townhome pending sales declined 14%.
These figures indicate that softer contract activity is affecting the broader market, although the reduction was more pronounced in the single-family sector.
However, pending sales are not guaranteed future closings, and the timing of completed transactions can vary.
For sellers, the decline reinforces the importance of realistic pricing and understanding buyer expectations.
For buyers, softer contract activity may provide opportunities to negotiate, particularly on properties that have remained available for longer periods.
The key question moving forward will be whether pending sales begin to recover as Miami-Dade County enters its winter selling season.
🔻 Down 12% year-over-year
Months of inventory declined 12% compared with October 2025.
This statistic measures how long the available supply of properties would take to sell at the prevailing sales pace.
The reduction indicates that Miami-Dade County’s overall reported supply measure has tightened over the past year.
This is consistent with the 8% decline in active inventory.
However, the reduction is particularly interesting because closed and pending sales have also declined.
Despite softer transaction activity, the reported months-of-inventory measure has fallen.
The trend was evident across both major property sectors.
Single-family months of inventory declined 17%, while condo and townhome months of inventory fell 9%.
These figures suggest that supply conditions have tightened more significantly in the single-family sector.
However, the 18% decline in overall pending sales indicates that current buyer contract activity has also softened.
This demonstrates why months of inventory should always be considered alongside other market indicators.
A lower months-of-inventory figure does not automatically establish that every neighborhood favors sellers.
🔻 Down 12% year-over-year
Days on market declined 12% compared with October 2025.
This indicates that properties completing sales spent less time on the market than they did a year ago.
The improvement was evident across both major property sectors.
Single-family days on market declined 16%, while condos and townhomes recorded a 3% reduction.
These figures suggest that selling times improved more significantly in the single-family sector.
The reduction is particularly interesting because closed sales declined 11% and pending sales fell 18%.
Although fewer transactions are taking place, properties completing sales are moving through the market more quickly.
Reduced inventory may be contributing to this trend by limiting the number of alternatives available to buyers.
Changes in the mix of properties sold or more competitive pricing may also play a role.
However, the countywide figures do not establish exactly what caused the reduction in selling times.
For sellers, the improvement reinforces the importance of accurate pricing and effective presentation.
For buyers, it highlights the value of being prepared when suitable properties become available.
Nevertheless, faster selling times do not mean every property is selling quickly.
Homes that are overpriced, require significant improvements or face competition from similar listings may still spend extended periods on the market.
The key takeaway is that Miami-Dade County’s overall housing market is moving faster, but transaction activity remains softer than last year.
🔻 Down 7% year-over-year
New residential listings totaled 3,368 in October, a 7% decline compared with October 2025.
This indicates that fewer properties entered the market during the month.
The reduction was relatively similar to the 8% decline in active inventory.
However, new listings and active inventory measure different aspects of supply.
New listings represent properties entering the market during a particular period, while active inventory represents properties available at a given point.
The figures also reveal differences between property types.
Single-family new listings declined 11% to 1,323 homes, while condo and townhome listings fell 4% to 2,037 properties.
These figures indicate that fewer properties entered both major sectors compared with last October.
For buyers, reduced new listing activity may mean fewer fresh opportunities to consider.
For sellers, fewer newly listed competing properties can be beneficial.
However, the 18% decline in pending sales indicates that buyer contract activity has softened more substantially than new listing activity.
If these trends continue, it will be worth monitoring whether inventory remains relatively tight or begins to rebuild as the winter selling season progresses.
Miami-Dade County buyers are navigating a market where overall median prices have remained stable, inventory has tightened and transaction activity has softened.
The median sale price remained unchanged at $551,995, while active inventory declined 8%.
Meanwhile, closed sales decreased 11%, and pending sales fell 18%.
These figures suggest that buyers may have opportunities to negotiate, particularly on properties that have remained available for longer periods.
However, days on market declined 12%, indicating that properties completing sales are moving faster.
This means buyers should be prepared when a desirable, competitively priced property becomes available.
The experience will also depend heavily on property type.
Single-family buyers are seeing higher median prices and a substantial reduction in inventory, while condo and townhome buyers are experiencing relatively stable median prices and a smaller decline in available supply.
Buyers should focus on individual property values, recent comparable sales and the full cost of ownership rather than relying solely on countywide trends.
For condominium buyers, reviewing association fees, reserves, insurance and potential special assessments remains particularly important.
Miami-Dade County sellers are operating in a market where overall median prices have remained stable but transaction activity has declined.
However, reduced inventory and faster selling times provide some encouraging indicators.
The differences between property types are particularly important.
Single-family sellers are seeing higher median prices and a substantial reduction in available inventory.
Meanwhile, condo and townhome sellers are facing a slight decline in median sale price, despite reduced inventory.
Both sectors have experienced declines in pending contract activity.
This means realistic pricing and effective marketing remain essential.
Sellers should evaluate recent comparable sales within their specific neighborhood or community rather than assuming that countywide trends apply equally to every property.
Professional photography, thoughtful preparation and a strong marketing strategy can help a listing stand out.
For condo and townhome sellers, clear information about association fees, reserves, insurance and potential assessments can also help buyers make informed decisions.
For investors, Miami-Dade County’s October housing statistics present a market with stable overall median prices, reduced inventory and softer transaction activity.
The unchanged overall median sale price suggests that countywide pricing has remained relatively resilient.
However, the 11% reduction in total sales dollar volume and 18% decline in pending sales indicate that overall market activity has weakened.
The contrast between single-family homes and condos and townhomes highlights the importance of examining individual property sectors.
Single-family median prices increased 4%, while condo and townhome median prices declined 1%.
Investors should avoid interpreting countywide price stability as evidence that every property is experiencing the same trend.
Individual neighborhoods, property conditions and price ranges can vary significantly.
Opportunities may exist where properties have been listed for extended periods or sellers are motivated to negotiate.
However, financing costs, insurance, property taxes, maintenance, renovation expenses, association fees and potential special assessments should all be considered carefully.
Rental demand, realistic rental income and community restrictions are also important when evaluating investment properties.
A successful investment strategy should focus on property-level fundamentals rather than broad market averages alone.
Miami-Dade County’s October 2026 housing market is showing stable overall median prices, tighter inventory and faster selling times, despite a meaningful reduction in completed transactions and pending contracts.
The median sale price remained unchanged at $551,995, while closed sales declined 11% to 1,691 properties.
Active inventory decreased 8% to 16,779 properties, and pending sales fell 18% to 1,643 contracts.
Meanwhile, days on market declined 12%, months of inventory fell 12%, and new listings decreased 7% to 3,368 properties.
Total residential sales dollar volume declined 11% to approximately $1.7 billion.
Together, these figures suggest a market where reduced supply is accompanying stable median pricing but softer transaction activity.
However, the differences between property types remain important.
Single-family median prices increased 4% to $706,000, while condo and townhome median prices declined 1% to $397,500.
At the same time, single-family closed sales fell 12%, compared with a 10% decline in condo and townhome transactions.
Both sectors experienced faster selling times, but neither was immune to the slowdown in pending contract activity.
For sellers, reduced inventory and faster selling times offer some encouraging conditions, but accurate pricing and effective marketing remain essential.
For buyers, stable overall median prices may be reassuring, although conditions vary significantly by property type and neighborhood.
As Miami-Dade County moves toward the end of 2026, the key trends to watch will be whether pending sales recover, whether inventory continues to tighten and whether the differences between single-family homes and condos and townhomes persist.
For now, Miami-Dade County’s overall housing market remains active but selective, creating opportunities for buyers, sellers and investors who understand the importance of local market conditions and individual property values.
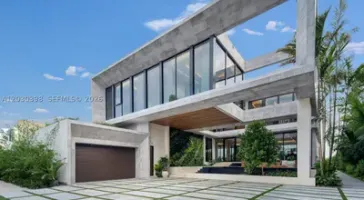
7 Beds | 6/2 Baths
Contact Devin at 301.602.1172
Offered at $49,500,000
More Info
7 Beds | 8/1 Baths
Contact James at ..
Offered at $35,000,000
More Info
6 Beds | 7/2 Baths
Contact Steven at ..
Offered at $21,900,000
More Info
7 Beds | 7/1 Baths
Contact William at 305.345.2023
Offered at $19,450,000
More Info
8 Beds | 8/1 Baths
Contact Chad at 305.400.9507
Offered at $14,900,000
More Info

or Create your MyHomes account today?
In only 30 seconds you will have full access to property, community info and SOLD data you can't get anywhere else.