Get Email Updates
Get an email the instant your dream home hits the market with your MyLogin account
Updated October 16, 2026 11:14AM EST



16 OCT
All Residential Properties
Martin County’s residential real estate market delivered an interesting combination of stronger completed sales, rising median prices and significantly tighter inventory in September 2026.
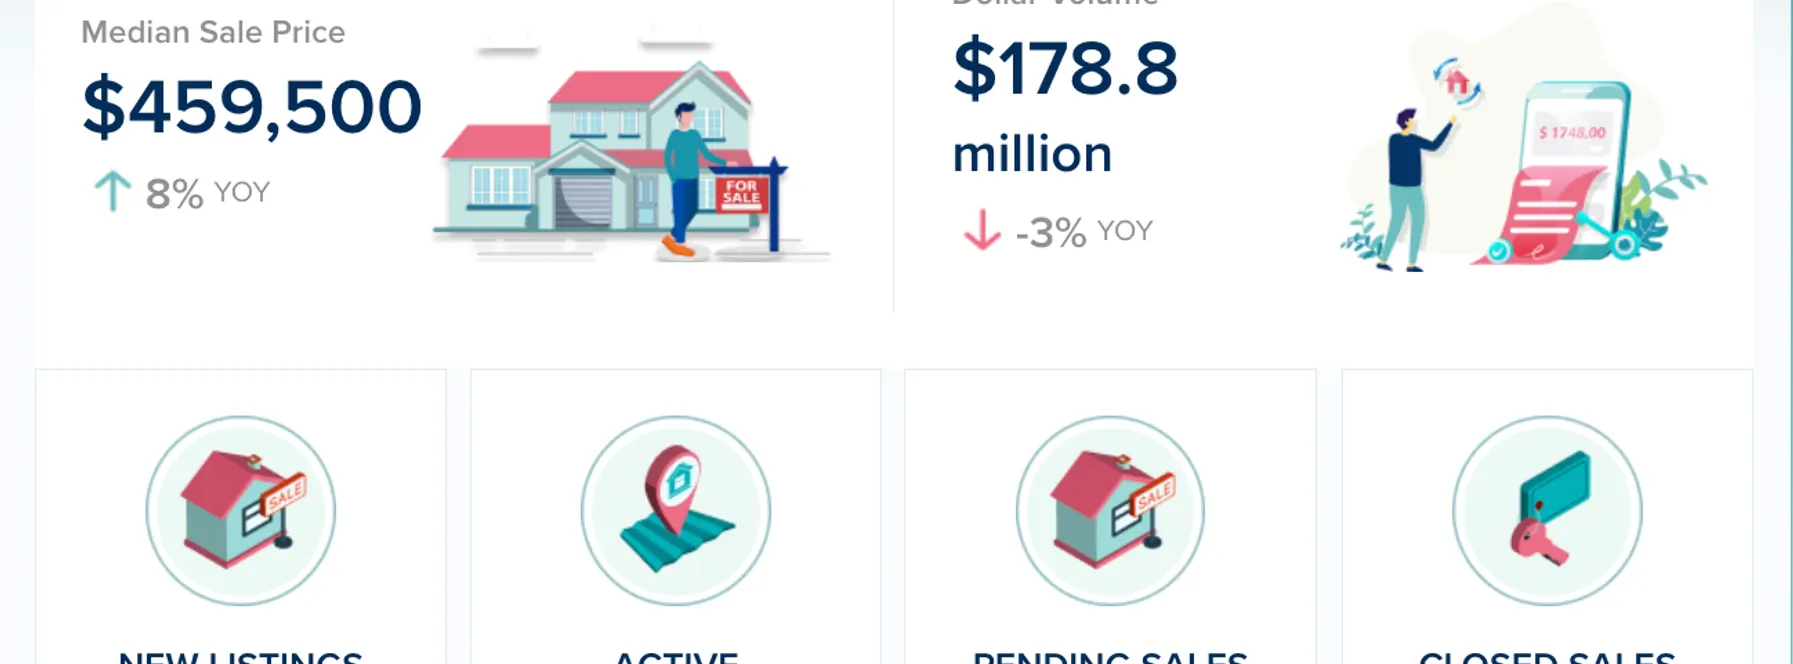
Across all residential property types, the median sale price reached $459,500, up 8% year-over-year, while closed sales increased 6%. Active inventory declined 21%, months of supply fell 31%, and days on market dropped an impressive 38%.
However, pending sales declined 4%, suggesting that current contract activity is not quite keeping pace with the improvement in completed transactions.
Perhaps the most interesting story is the difference between Martin County’s single-family and condo/townhome markets. While single-family sales activity softened, condos and townhomes recorded stronger sales and pending contracts, helping lift the overall residential market.
Here’s a closer look at September’s numbers.
📈 Up 8% year-over-year
The median sale price across Martin County’s residential market reached $459,500 in September, an 8% increase compared with September 2025.
Both major property sectors recorded higher medians.
Single-family homes reached $600,000, up 5%, while condos and townhomes reached $237,500, up 8%.
However, the countywide median is influenced by the mix of properties sold during the month. It should not be interpreted as every Martin County property appreciating by 8%.
In a relatively small market, changes in the types and price ranges of properties sold can have a particularly noticeable effect on the median.
For buyers and sellers, recent comparable sales within the specific neighborhood or community remain the most useful guide to individual property values.
📈 Up 6% year-over-year
Martin County recorded 278 residential closed sales in September, a 6% increase compared with last year.
This is an encouraging result, particularly given the significant reduction in available inventory.
However, the two major property sectors performed differently.
Single-family closed sales declined 4%, while condo and townhome sales increased 14%.
That contrast suggests the attached-home sector contributed important momentum to the overall residential market.
The increase in completed transactions is positive, but it should also be considered alongside the decline in pending sales when evaluating whether that momentum is likely to continue.
🔻 Down 21% year-over-year
Active residential inventory declined 21%, leaving Martin County buyers with substantially fewer properties available than they had a year ago.
Both major sectors experienced significant reductions.
Single-family inventory fell 18% to 682 homes, while condo and townhome inventory declined 25% to 463 properties.
The sharper contraction in the attached-home sector is particularly notable because condo and townhome sales activity also increased.
For sellers, fewer competing listings can create an advantage.
For buyers, reduced inventory makes it important to monitor new opportunities carefully, particularly in desirable communities and popular price ranges.
🔻 Down 4% year-over-year
Pending sales declined 4% compared with September 2025.
This provides an important counterpoint to the 6% increase in closed sales.
Pending contracts can offer an indication of transactions potentially moving toward future closings, although not every contract ultimately closes.
The underlying sectors again tell different stories.
Single-family pending sales declined 12%, while condo and townhome pending sales increased 11%.
That suggests current contract activity is considerably stronger in the attached-home sector than in the single-family market.
The overall decline is relatively modest, but it will be worth watching as Martin County moves into the final quarter of 2026.
🔻 Down 31% year-over-year
Months of supply declined 31%, confirming that Martin County’s residential market has tightened considerably.
This statistic measures how long the current inventory would take to sell at the prevailing pace of sales.
A substantial reduction generally means fewer available properties relative to transaction activity.
Both major property sectors experienced significant declines, with single-family months of inventory falling 29% and condo/townhome supply declining 35%.
However, tighter inventory does not automatically mean every property will attract immediate interest.
Pricing, condition, location and buyer affordability remain important factors in determining how quickly individual homes sell.
🔻 Down 38% year-over-year
Days on market recorded one of September’s most impressive changes, falling 38% compared with September 2025.
Properties that successfully sold moved considerably faster than they did a year ago.
This improvement was visible across both major residential sectors.
Single-family days on market declined 37%, while condo and townhome selling times dropped an even more substantial 46%.
That is an encouraging sign for sellers, particularly when combined with reduced inventory.
Martin County is not only recording more completed residential transactions overall — successful listings are also spending significantly less time on the market.
However, the decline in pending sales suggests it is important not to assume that faster selling times will automatically translate into continued increases in transaction volume.
🔻 Down 4% year-over-year
New residential listings declined 4% compared with September 2025.
The reduction is relatively modest, but it comes at a time when active inventory is already down 21%.
Both major sectors recorded fewer new listings.
Single-family new listings declined 5%, while condo and townhome new listings fell 4%.
If fewer properties continue to enter the market, available supply may remain constrained.
However, softer pending activity in the single-family sector could partially offset this trend by slowing the pace at which some listings move toward closing.
Martin County buyers are facing considerably fewer available properties than they had a year ago.
Active inventory is down 21%, months of supply has declined 31%, and properties that successfully sell are moving 38% faster.
However, the experience differs depending on property type.
Single-family buyers face reduced inventory, but pending sales are down 12%, suggesting buyer activity remains relatively measured.
Condo and townhome buyers are encountering a different environment. Inventory has declined 25%, while closed and pending sales have both increased.
That combination may mean desirable attached properties attract attention more quickly.
Regardless of property type, buyers should carefully evaluate pricing, condition and recent comparable sales.
For condos and townhomes, HOA fees, reserve funding, insurance, special assessments and rental restrictions should also be thoroughly reviewed before purchasing.
Martin County sellers benefit from substantially less competition than they did last September.
Active inventory is down 21%, new listings have declined 4%, and successful sales are happening considerably faster.
Overall closed sales also increased 6%.
However, sellers should pay attention to the differences between property types.
Single-family pending activity has softened, while the condo and townhome sector has recorded stronger sales and contracts.
That makes neighborhood-level and property-specific pricing especially important.
Reduced inventory can create an advantage, but accurate pricing, strong presentation and effective marketing remain essential for attracting qualified buyers.
For investors, Martin County’s tightening inventory and stronger overall sales activity create an interesting market to evaluate.
However, the differences between single-family and attached properties reinforce the importance of analyzing each opportunity individually.
The condo and townhome sector has experienced stronger transaction activity, but association expenses, reserves, assessments, insurance and rental restrictions can significantly affect investment returns.
Single-family properties may offer different ownership costs and rental opportunities, but financing, taxes, maintenance and realistic rental income still require careful consideration.
Rather than relying solely on countywide median price changes, investors should focus on the financial fundamentals of the individual property and its surrounding market.
Martin County’s September 2026 residential market delivered stronger completed sales, significantly tighter inventory and dramatically faster selling times.
The median sale price increased 8% to $459,500, while closed sales rose 6%.
At the same time, active inventory declined 21%, months of supply fell 31%, and days on market dropped an impressive 38%.
New listings were also down 4%, reinforcing the broader reduction in available supply.
However, pending sales declined 4%, suggesting that current contract activity remains somewhat softer than the completed-sales figures alone might indicate.
The difference between property types is particularly important.
Martin County’s condo and townhome market recorded stronger closed and pending sales, while the single-family sector experienced declines in both categories.
For sellers, reduced competition and faster successful sales are encouraging, but realistic pricing remains essential.
For buyers, limited inventory makes preparation important, although negotiating opportunities will continue to vary by neighborhood, property type and individual listing.
As Martin County moves into the final quarter of 2026, the key trend to watch will be whether stronger condo and townhome activity continues to support the overall market — and whether single-family pending sales begin to recover.
For now, Martin County’s residential market is defined by constrained supply, faster successful sales and a meaningful divide between its single-family and attached-home sectors.
6 Beds | 6/1 Baths
Contact Craig at ..
Offered at $2,995,000
More Info
5 Beds | 4 Baths
Contact Jonathan at ..
Offered at $2,396,000
More Info
5 Beds | 3 Baths
Contact Iryna at ..
Offered at $1,275,000
More Info
3 Beds | 2/1 Baths
Contact Aaron at ..
Offered at $1,195,000
More Info
4 Beds | 4/1 Baths
Contact Brian at ..
Offered at $858,990
More Info

or Create your MyHomes account today?
In only 30 seconds you will have full access to property, community info and SOLD data you can't get anywhere else.