Get Email Updates
Get an email the instant your dream home hits the market with your MyLogin account
Updated September 16, 2026 10:54AM EST



16 SEP
All Residential Properties
Martin County’s residential real estate market became considerably tighter in August 2026, with fewer properties available, less overall supply and homes selling substantially faster than they did a year ago.
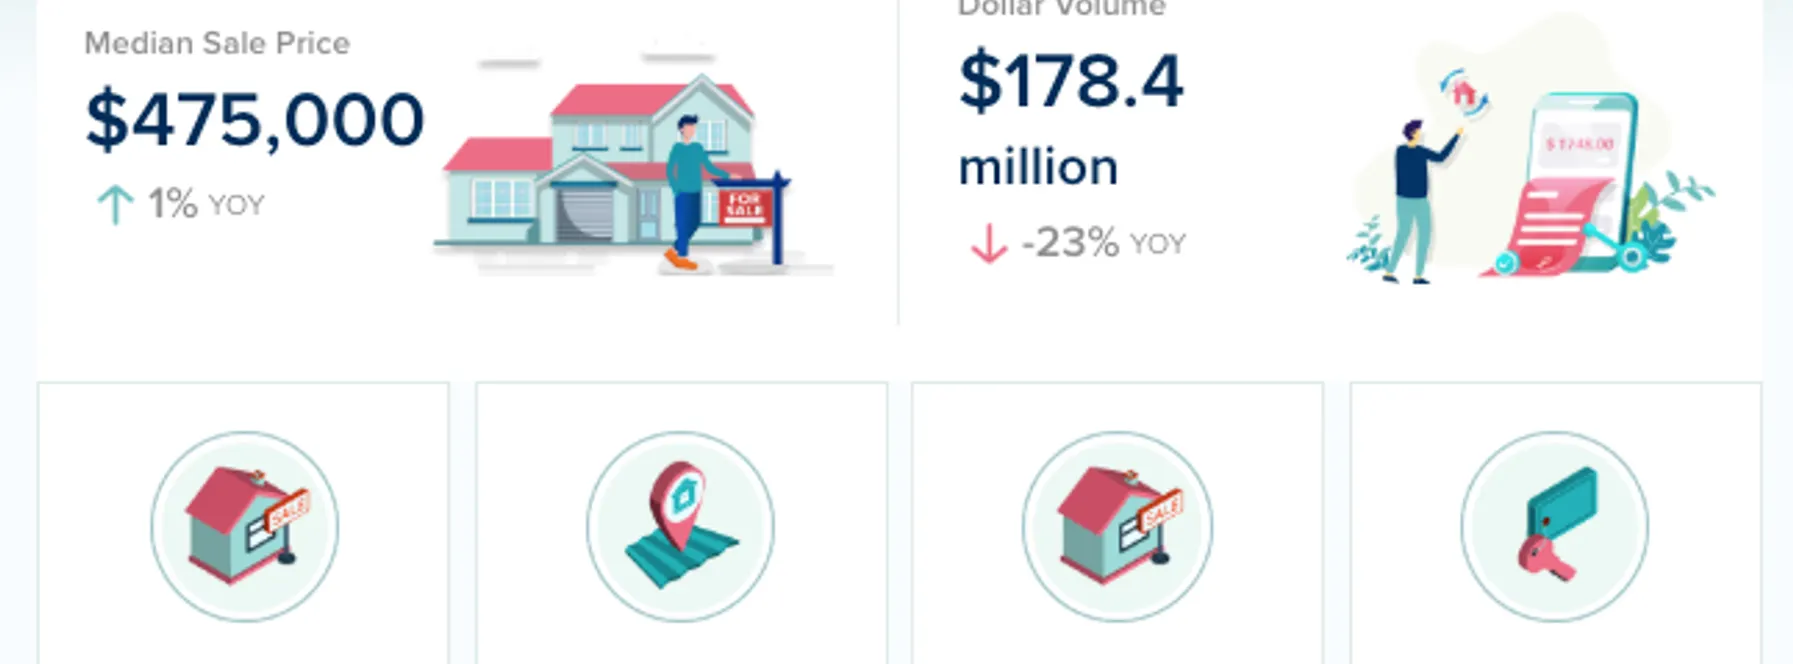
Across all residential property types, active inventory declined 20%, months of supply fell 31%, and days on market dropped an impressive 29%. The median sale price remained relatively stable, increasing 1% to $475,000.
However, there is an important counterpoint: closed sales fell 15% compared with August 2025, while pending sales were essentially unchanged.
The result is an unusual combination of tighter supply and faster selling times alongside lower overall transaction volume — making this a market where the individual property and price point matter enormously.
Here’s a closer look.
📈 Up 1% year-over-year
Martin County’s median residential sale price was essentially stable in August, increasing just 1% to $475,000.
The combined figure is particularly interesting when we look at the two major property segments underneath it.
The single-family median reached $656,900, up 13%, while the condo and townhome median increased 21% to $277,500.
Those larger increases should be interpreted with some caution, particularly given the relatively small number of transactions during the month. Changes in the mix and price points of properties sold can have a significant effect on median prices.
The much smaller 1% change across all residential properties reinforces the importance of looking at individual communities and comparable sales rather than relying on one countywide percentage.
🔻 Down 15% year-over-year
Closed sales declined substantially, with 15% fewer residential transactions completed than in August 2025.
This softness was visible across both major segments. Single-family closed sales declined 11%, while condo and townhome sales fell 23%.
That is important context because it shows the decline was not isolated to one property type.
Martin County has considerably less inventory than it did a year ago, which may be limiting the number of transactions that can take place. At the same time, buyers remain selective about value.
🔻 Down 20% year-over-year
There were one-fifth fewer residential properties available for sale than there were last August.
Both major segments contributed to the decline: single-family inventory fell 22%, while condo and townhome inventory declined 20%.
For buyers, that means considerably less choice. For sellers, it means fewer competing properties on the market.
🔻 Down 1% year-over-year
Pending sales were essentially unchanged from last year, declining just 1%.
This is somewhat more encouraging than the 15% decline in completed transactions and suggests activity entering the pipeline is closer to last year’s levels.
The underlying segments moved in opposite directions, however. Single-family pending sales declined 7%, while condo and townhome pending sales increased 9%.
That difference will be worth watching as we move through the remainder of the year.
🔻 Down 31% year-over-year
Martin County had just 4.3 months of residential inventory available in August, a substantial 31% decline from last year.
That puts the overall county market on the seller-leaning side of balanced from a supply perspective.
Once again, property type makes a difference.
Single-family homes had just 3.4 months of supply, creating a tighter seller-favored environment, while condos and townhomes had 5.5 months, placing that sector closer to balanced conditions.
🔻 Down 29% year-over-year
This is one of August’s most notable statistics.
Martin County residential properties that sold spent 29% less time on the market than they did a year ago.
That is particularly interesting given the 15% decline in closed sales. Fewer properties are selling overall, but the homes that successfully attract buyers are selling considerably faster.
This may point to an increasingly divided market between properties that are appropriately priced and well-positioned, and those that fail to meet buyers’ expectations.
🔻 Down 2% year-over-year
New listing activity was relatively stable, declining just 2%.
However, with overall active inventory already down 20%, the market is not receiving enough additional supply to meaningfully rebuild buyer choice.
The underlying segments differed here as well. Single-family new listings declined 7%, while condo and townhome listings increased 6%.
Martin County buyers have considerably fewer properties to choose from than they did a year ago.
With active inventory down 20% and overall months of supply at 4.3, well-priced properties can move quickly. The 29% decline in days on market reinforces the importance of being prepared when the right home appears.
However, the 15% decline in closed sales shows that buyers are not simply purchasing everything available.
That means there can still be negotiating opportunities on properties that are overpriced, require significant improvements or have remained on the market longer than comparable homes.
Property type matters too. Single-family buyers face a tighter 3.4-month supply, while condo and townhome buyers have more breathing room at 5.5 months.
Martin County sellers face substantially less competition than they did last year.
Inventory is down 20%, months of supply has fallen 31%, and properties that sell are moving 29% faster.
Those are meaningful advantages.
However, the decline in closed sales demonstrates why realistic pricing remains critical. Buyers have fewer choices, but they remain selective.
Sellers should pay close attention to recent comparable sales within their specific neighborhood, community and price range rather than relying solely on countywide trends.
For investors, Martin County’s tightening supply can create attractive longer-term fundamentals, but August’s softer transaction volume reinforces the need for careful property selection.
Single-family properties face particularly limited supply, while the condo and townhome market offers more inventory and potentially greater negotiating room.
Investors considering condos should also thoroughly investigate HOA finances, reserves, insurance, special assessments and rental restrictions alongside the usual considerations of taxes, maintenance, financing and expected rental income.
Martin County’s August 2026 real estate statistics reveal a market that is significantly tighter and faster-moving than it was a year ago, but with fewer transactions taking place.
Active inventory declined 20%, months of supply fell 31% to 4.3 months, and days on market dropped an impressive 29%.
Yet closed sales declined 15%, while pending sales were essentially flat and the overall median sale price increased just 1% to $475,000.
That combination makes August particularly interesting. Reduced inventory is creating scarcity, but it has not eliminated buyer selectivity.
The difference between property types remains important as well. Single-family homes are operating with just 3.4 months of supply, compared with 5.5 months for condos and townhomes.
For sellers, reduced competition and faster selling times are encouraging, but accurate pricing remains essential. For buyers, preparation matters in a tighter market, but opportunities can still exist where a property has been poorly positioned.
As we move toward the final quarter of 2026, whether Martin County’s dramatically tighter supply eventually produces stronger transaction activity will be one of the most important trends to watch.
6 Beds | 6/1 Baths
Contact Craig at ..
Offered at $2,995,000
More Info
3 Beds | 2/1 Baths
Contact Andrea at ..
Offered at $1,600,000
More Info
3 Beds | 3 Baths
Contact Sophie at ..
Offered at $1,374,990
More Info
3 Beds | 2/1 Baths
Contact Patricia at ..
Offered at $724,999
More Info

or Create your MyHomes account today?
In only 30 seconds you will have full access to property, community info and SOLD data you can't get anywhere else.